Stanbic Bank Botswana’s first-half profit after tax rose 16 percent to P354 million, even as currency volatility, liquidity constraints and weak diamond-linked activity cloud the second half.
GAZETTE REPORTER
Stanbic Bank Botswana Limited (SBBL) posted higher first-half profit but says financial resilience will remain a priority as modest growth, constrained market liquidity and continued volatility in the pula against major currencies shape the rest of 2026.
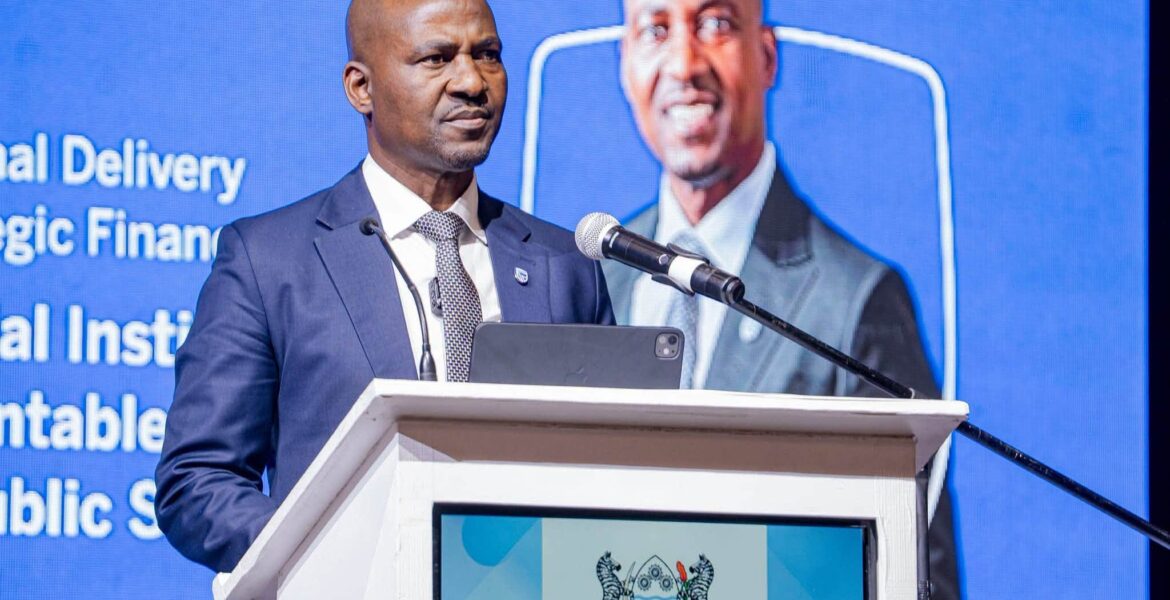
In their review of the bank’s condensed consolidated interim financial statements for the half year ended 30 June 2026, Chief Executive Officer Chose Modise and board chairperson Dr Tebogo Matome said the outlook to the end of the year remained sensitive to a range of economic pressures.
“The outlook to the end of the year remains sensitive, shaped by modest economic growth, modest market liquidity, potential monetary policy changes, and the continued volatility of the Pula against major currencies,” they said.
Risk backdrop
The bank said the implementation of tax and labour market reforms could further increase operating costs for businesses, reduce consumer spending capacity and contribute to higher credit risk in selected sectors.
It also pointed to ongoing fiscal consolidation and subdued activity in diamond-related industries as factors shaping the operating environment.
Earnings rise
Despite these conditions, SBBL reported a 16 percent increase in Profit After Tax to P354 million for the half year, up from P304 million in June 2025.
The bank said prevailing macroeconomic conditions constrained balance sheet growth, resulting in subdued deposit growth and a contraction in asset balances. It described this as part of a disciplined approach to optimising risk-adjusted returns while protecting net interest margins and managing credit impairments amid growing household and business income pressures.
Net Interest Income increased by 12 percent year on year. Total interest income grew by 13 percent, supported by improved returns on liquid assets and investment securities, although interest income from loans and advances declined by 5 percent.
Interest expense increased by 14 percent, reflecting higher funding costs during the period.
Resilience plan
Against the challenging backdrop, the bank said it would strengthen portfolio oversight, accelerate non-funded income growth, drive quality asset expansion and advance digital and operational transformation initiatives.
“Strategic priorities include strengthening portfolio oversight, accelerating non-funded income growth, driving quality asset expansion, and advancing digital and operational transformation initiatives,” Modise and Dr Matome said.
The bank said excess liquidity was strategically deployed into short-term negotiable securities offering attractive risk-adjusted returns. These actions, it said, helped offset slower loan book growth and supported continued earnings growth.
Kgolo strategy
Its Kgolo Strategy remains the framework guiding execution and decision-making, with three strategic priorities focused on sustainable growth, enhanced resilience and superior client outcomes.
The bank also highlighted its Ledi-Lame Financial Rehabilitation Programme, designed to assist customers experiencing financial distress, and the Legae Housing Programme, which advances its sustainability pillar.
Modise and Dr Matome said the bank would continue advancing its digital, regulatory and operational transformation agenda while remaining focused on long-term value for shareholders, clients, employees and the broader stakeholder community.