BoB removes prime-rate ban as liquidity improves, handing banks greater pricing freedom while borrowers face renewed interest-rate risk
BONGANI MALUNGA
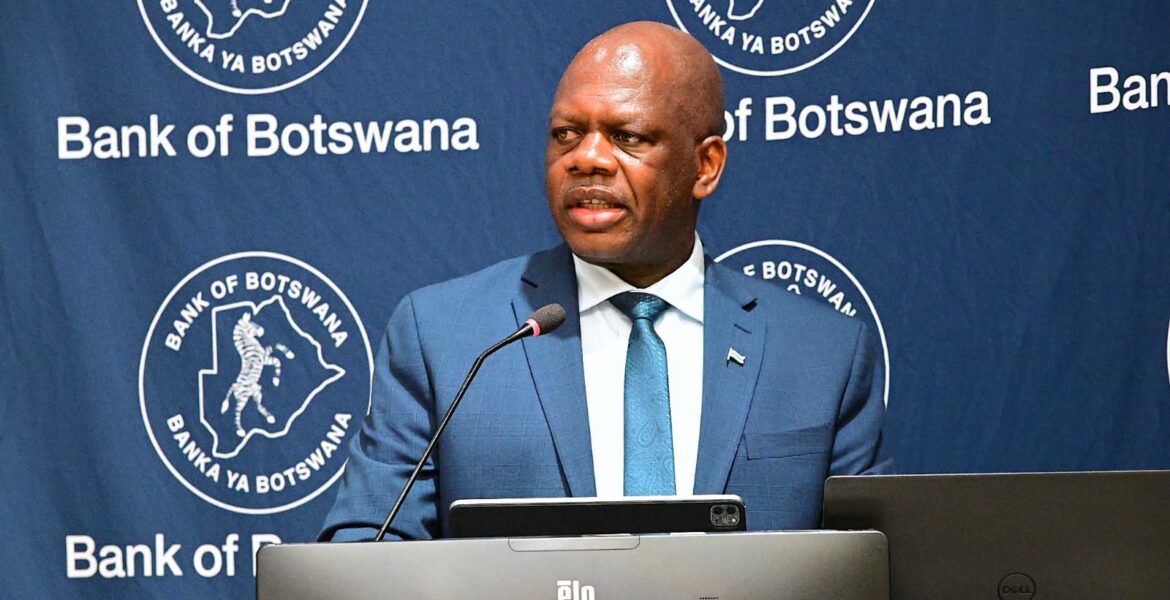
Commercial banks have regained the freedom to increase their prime lending rates after the Bank of Botswana’s Monetary Policy Committee (MPC) unanimously lifted a moratorium that had prevented them from doing so.
The decision effectively restores banks’ ability to adjust the benchmark rate from which the cost of many loans is calculated, giving lenders greater control over how they price credit as Botswana’s financial system emerges from a prolonged liquidity squeeze.
The change means the protection that prevented banks from raising prime lending rates has disappeared. Should individual banks decide that their costs or market conditions justify an increase, households and businesses with loans linked to prime could face higher repayments.
NO AUTOMATIC RISE
The MPC’s decision does not mean lending rates will automatically rise. In fact, the central bank believes conditions that previously placed pressure on banks have improved considerably, potentially reducing the need for lenders to charge customers more.
“Domestic liquidity has improved since the last quarter of 2025, supported by increased government funding and spending, increased diamond receipts, and adjustments to monetary policy operations. This has moderated funding costs, potentially lowering lending interest rates with improved prospects for policy transmission,” the Bank of Botswana said.
As per BoB’s assessment, banks now have more money circulating within the financial system and are finding it less expensive to secure funding than during the height of the liquidity shortage.
BALANCING ACT
While banks have regained the ability to increase prime rates, improving liquidity could simultaneously give them room to compete for customers by keeping lending rates unchanged or offering more attractive pricing to strong borrowers.
For commercial banks, lifting the moratorium restores an important tool for managing their lending businesses. When the cost of obtaining money rises, banks ordinarily have the option of passing some of that cost to borrowers through changes in lending rates. The moratorium restricted that flexibility.
The central bank said lifting the restriction was also consistent with its broader preference for maintaining a liberalised financial market, where lending prices are allowed to respond more freely to market conditions.
CONSUMER PERSPECTIVE
From a consumer perspective, the significance will largely depend on what individual banks do next.Prime lending rates generally serve as a starting point when banks determine what customers pay on certain loans. A customer may, for example, be charged prime plus or minus an agreed margin depending on their risk profile and loan arrangement.
Businesses borrowing to finance expansion, equipment or working capital could also see financing costs rise. However, the same improved liquidity that persuaded the MPC to remove the restriction could work in borrowers’ favour.
With funding pressures easing and banks competing for lending business, the removal of the moratorium may ultimately produce greater differences in pricing between banks rather than an across the board rise in borrowing costs.