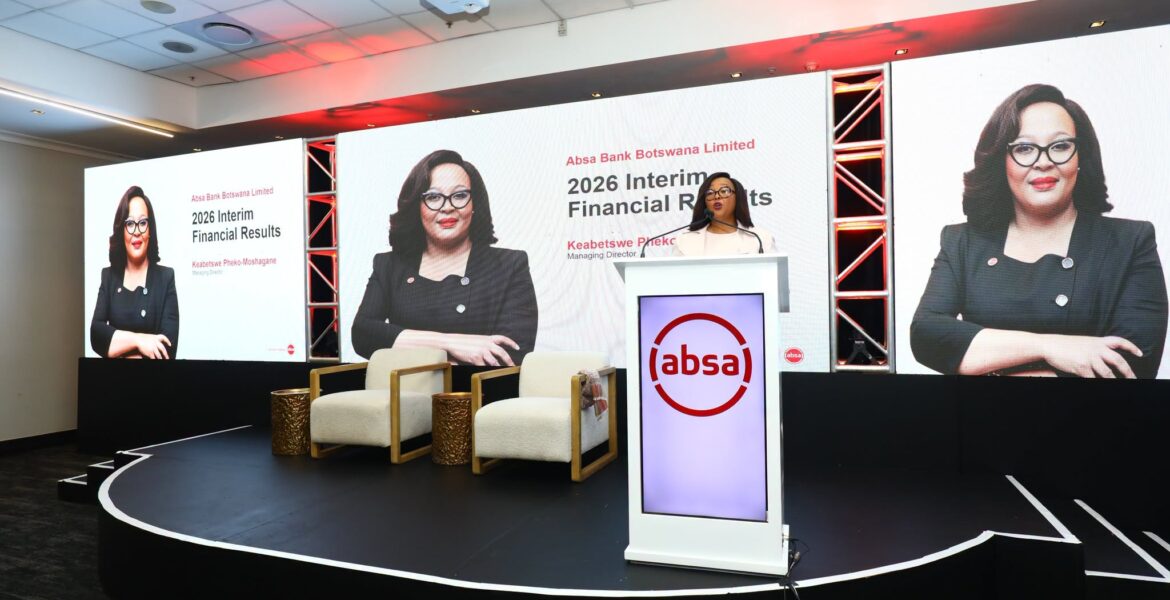
A 63 percent surge in non-interest income helped Absa Bank Botswana offset pressure from higher funding costs and rising expected credit losses.
GAZETTE REPORTER
Absa Bank Botswana’s non-interest income rose 63 percent to P561 million in the six months ended June 30, 2026, accounting for about 44 percent of the bank’s total income.
The figures are contained in the bank’s condensed consolidated interim financial statements.
Non-interest income is revenue earned from banking activities other than lending and interest, including fees and commissions, foreign exchange transactions, card and payment services and other financial activities.
The increase came as net interest income, the difference between interest earned and interest paid, declined 4 percent to P727 million despite growth in interest-earning assets.
Funding Squeeze
Effective interest income increased 11 percent to P1.28 billion, while effective interest expense rose 40 percent to P555 million.
Absa said the increase in interest expense reflected elevated funding costs during the first quarter following market liquidity pressures in 2025. Liquidity conditions improved significantly in the second quarter, reducing funding costs and helping margins recover towards the end of the reporting period.
“The strong growth in non-interest income improved revenue diversification and helped offset pressure on net interest margins experienced during the first quarter, contributing significantly to overall profitability,” board chairperson Cosmas Moapare and managing director Keabetswe Pheko-Moshagane said in the results.
Credit Risk
Expected credit losses more than doubled, rising 104 percent to P136 million from P67 million. The bank attributed the increase to changes in portfolio risk profiles, increased lending utilisation and updated forward-looking macroeconomic assumptions.
Operating expenses increased 4 percent to P671 million. Staff and infrastructure costs rose 9 percent and remained the largest cost component, while administration and general expenses declined 3 percent to P282 million.
Loans Contract
Total assets fell 6 percent to P25.4 billion from P26.9 billion at December 2025, mainly because of lower interbank placements and customer lending balances. This was partly offset by increased investment in government securities and trading assets.
Net loans and advances to customers declined 3 percent to P18.1 billion from P18.5 billion.
Personal and Private Banking loans increased marginally to P11.9 billion, while Business Banking loans grew 7 percent to P1.6 billion. Corporate and Investment Banking loans declined 7 percent to P4.5 billion.
Outlook Risks
Absa said Botswana’s economic outlook remains cautiously optimistic and expects growth of 3.1 percent in 2026, supported by a recovery in diamond production and trading and improved performance in selected non-mining sectors.
The bank expects inflation to remain elevated, with the central bank projecting average inflation of 8.7 percent in 2026.
It identified geopolitical tensions, uncertainty in global diamond markets, recurring foot-and-mouth disease outbreaks and El Niño-related drought conditions among the risks to the outlook.
Absa said its priorities include responsible lending, deeper focus on transactional activity, liquidity deployment, technology stability, cybersecurity, fraud prevention and stronger controls.